The Institutional Bridge and the Yield-Bearing Standard
If you hold stablecoins or follow tokenization, 2025 changed the entire playbook.
Here is what actually happened, why it matters for your portfolio, and what to watch in 2026.
The Big Shift
The old model of parking capital in USDC or USDT with 0% returns broke down in 2025.
Rates stayed high. Opportunity cost became real. Capital rotated fast into yield-bearing stablecoins.
Tokens like USDtb (Ethena) and USDO (Usual) passed on Treasury yields directly to users. That single design tweak triggered billions in flow and changed how on-chain “cash” functions.
Meanwhile, the line between TradFi and DeFi blurred completely.
BlackRock, Franklin Templeton, and Fidelity didn’t just “experiment.” They became liquidity engines.
DeFi protocols turned into front ends for tokenized TradFi products.
Private credit came back, but with cleaner underwriting and stronger collateral. The “degen loan” era is out. Asset-backed lending is in.
Where the Market Stood in Late 2025
Where the Market Stood in Late 2025
-
Stablecoins: ~$225B market cap
-
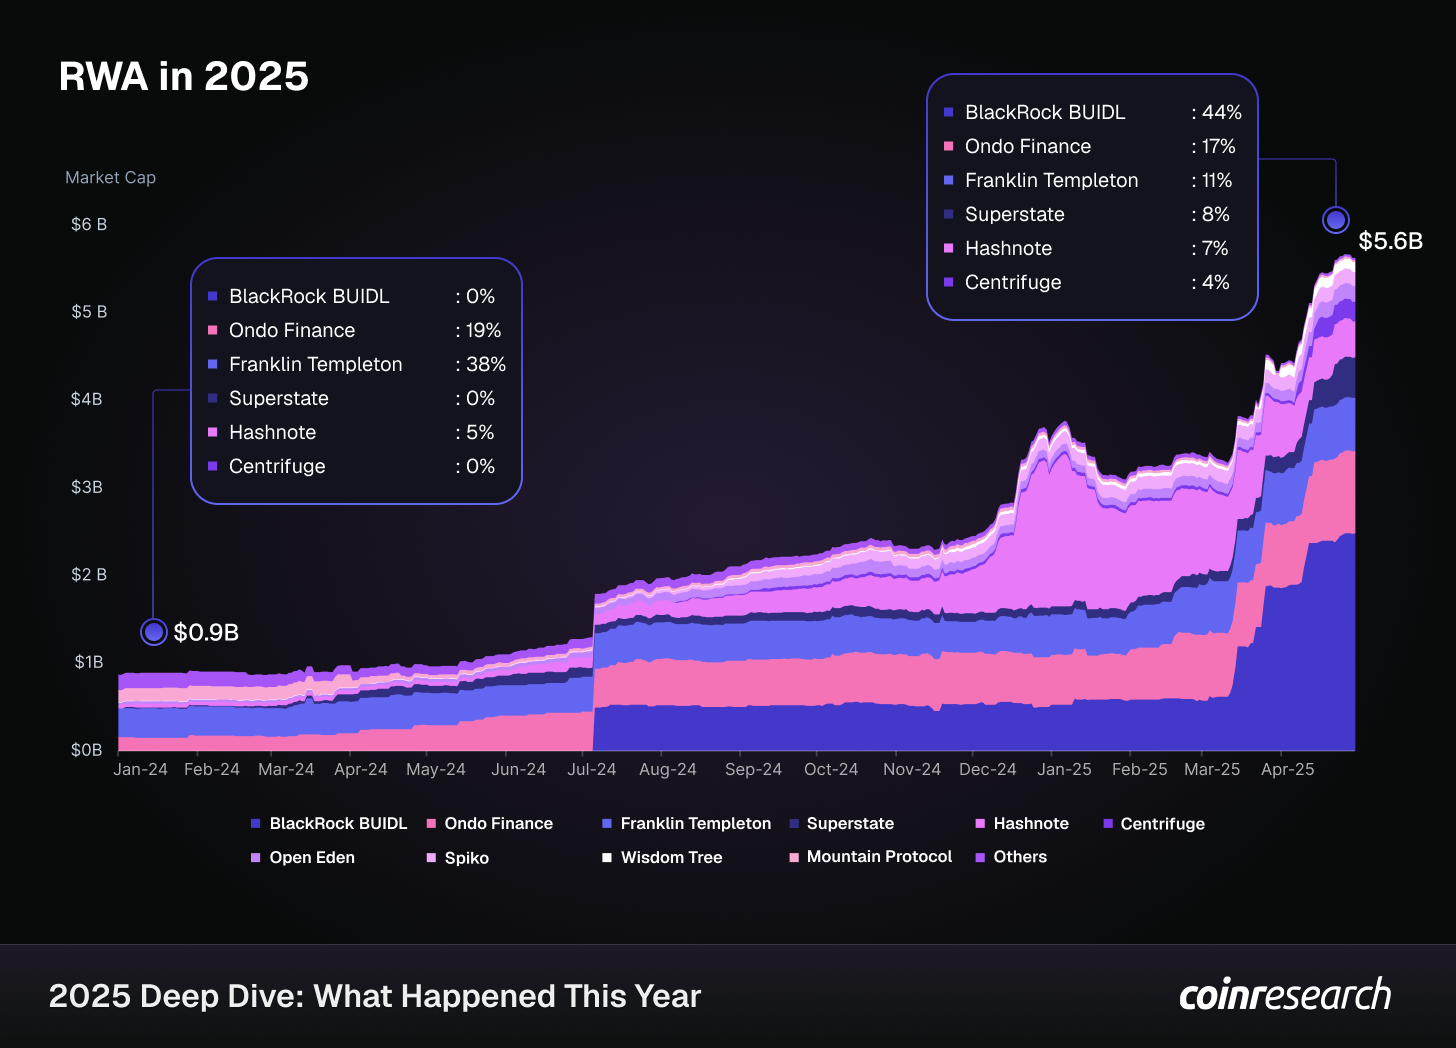
Tokenized Treasuries: $5.6B TVL (+500% YoY)
-
Private Credit: ~$750M to $900M, quality over quantity
-
Tokenized Real Estate & Equities: still niche, fragmented, and illiquid
The RWA landscape split into two dominant ends:
1. Sovereign-Grade Assets
Short duration, high trust, high liquidity.
BlackRock, Franklin Templeton, and Franklin’s BENJI fund lead here.
2. DeFi-Native Credit
Illiquid, high yield, higher risk.
Led by Maple, Centrifuge, and Goldfinch.
Everything in the middle, like real estate or tokenized equities, struggled to find product-market fit for the time being.
What Actually Drove the 2025 Cycle
Institutions actually showed up.
BlackRock’s BUIDL fund crossed $1B by March and accounted for over 40% of the tokenized Treasury market by April.
Protocols like Frax integrated it into their stablecoin models.
BUIDL wasn’t just a product, it became a blueprint.
Stablecoin holders demanded yield.
Hold USDC for 0%, or USDtb for ~5%? In 2025, the market voted with its feet.
Private credit matured.
Maple took around 67% of market share, shifting toward receivables-backed and real-economy loans.
Even with Treasury yields at 5%, tokenized credit held its own through better underwriting and more transparent terms.
Regulation found footing.
-
The GENIUS Act progressed in the U.S.
-
MiCA activated in the EU
-
Hong Kong and Singapore led on cross-border tokenized MMFs
Clearer rules invited faster movement, and serious capital.
What to Watch in 2026
RWA momentum is far from over. As we head into 2026, here are two early signals to watch:
1. Yield-Bearing Stablecoins Go Mainstream
USDtb and USDO triggered a design shift across the stablecoin market. In 2026, expect more issuers to follow. The zero-yield model may not survive another cycle.
2. Institutions Choose Chains
BlackRock, Franklin Templeton, and Apollo aren’t just tokenizing—they’re picking infrastructure. The chains they adopt (and custody with) will define the next phase of capital movement.
→ Six more key 2026 catalysts are covered in our full research, including AI-native portfolios, on-chain repo markets, and real estate tokenization.
How to Position for 2026
Retail investors and crypto-native allocators are already adjusting. Two practical shifts to consider:
1. Don’t Let Stablecoins Sit Idle
If you’re still holding USDC or USDT with 0% return, you’re missing the most basic on-chain opportunity. Cash now earns.
2. Follow the Regulated Flows
When a fund or stablecoin earns approval in markets like Singapore or the EU, it’s a green light. Big capital often follows quickly.
→ The full research includes portfolio models, RWA type blending strategies, and our long-term investment thesis through 2030.
Bottom Line
RWAs are no longer a side story. They’re now core infrastructure.
2025 was the inflection point: real yield, regulatory clarity, and institutional distribution are reshaping capital markets on-chain.
The winners in 2026 won’t just be token tickers. They’ll be the protocols and platforms that control settlement, custody, and compliant access.
Want the full breakdown?
We just released an in-depth research report:
“State of Real World Assets 2025: The Institutional Bridge & Yield-Bearing Standard”
Includes:
-
Complete sector map
-
Governance token breakdown (ONDO, MANTRA, Centrifuge)
-
Stablecoin market structure
-
Institutional flows
-
Regulatory scorecard by region
-
Infrastructure and protocol landscape
-
2026 catalysts, risks, and investment theses
Read the full report on CoinResearch AI, for just $9/mo during our holiday sale